An Overview of Discounted Cash Flow (DCF) Valuation
Introduction
Discounted Cash Flow (DCF) valuation is one of the most widely used intrinsic valuation techniques for estimating the present value of a business based on the cash flows it is expected to generate in the future. Unlike relative valuation, which compares a company with peers using market-based multiples, DCF valuation focuses primarily on the company’s own operating performance, investment requirements, growth prospects and risk.
The underlying idea is straightforward: a business is worth the present value of the cash that it can generate for its providers of capital over its economic life. However, applying this principle requires careful assumptions about future cash flows, discount rates, growth and capital structure.
1. Understanding the DCF Model
A DCF model estimates the value of an asset or business by forecasting future free cash flows and discounting those cash flows back to their present value. The approach is based on the premise that the value of an investment is linked to the economic benefits it is expected to produce.
For example, consider a lemonade stand. A potential buyer would not look only at the amount of cash the stand has today. The buyer would also consider the cash the business is expected to generate in future years and the risks associated with receiving that cash. DCF valuation formalises this logic into a financial model.
2. The Foundation: Time Value of Money
The foundation of DCF valuation is the time value of money. A rupee received today is generally worth more than a rupee received in the future because money available today can be invested and because future cash flows are subject to uncertainty and risk.
Consequently, future cash flows cannot simply be added together at their nominal values. Each expected cash flow must be converted into its equivalent value today by applying an appropriate discount rate. This process is known as discounting.
The present value of a future cash flow can be represented as:
PV = Future Cash Flow / (1 + r)^t
where r represents the discount rate and t represents the period in which the cash flow is received.
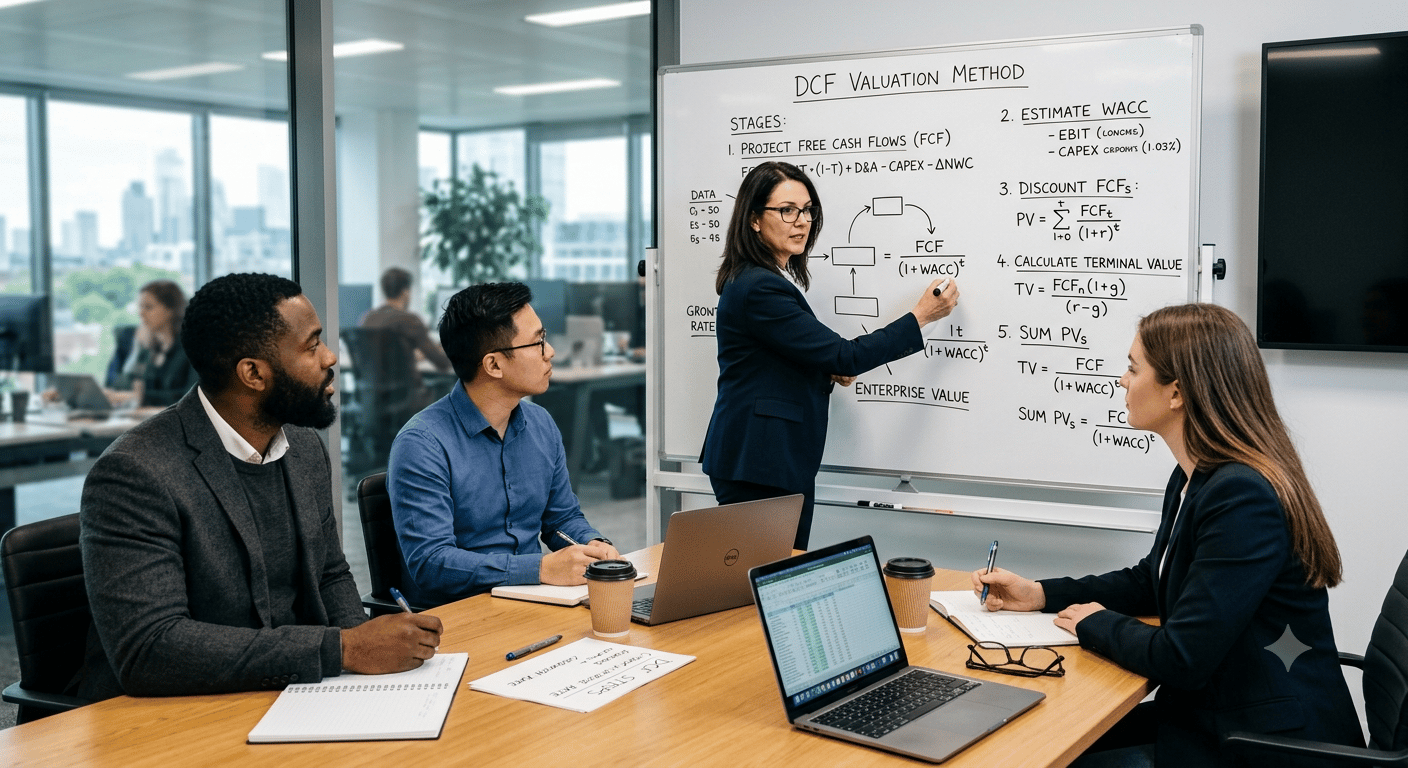
3. The Five-Step DCF Valuation Framework
Step 1: Forecast Free Cash Flow
The first step is to forecast the free cash flow that the business is expected to generate during an explicit forecast period. A five-year forecast is common for mature businesses, while businesses undergoing significant growth may require a longer period.
Free Cash Flow (FCF) represents the cash generated from operations that remains after accounting for operating requirements and the capital investment necessary to maintain or grow the business.
FCF = EBIT × (1 − Tax Rate) + D&A − Capital Expenditure − ΔNon-Cash Working Capital
The quality of the DCF depends heavily on the assumptions used for revenue growth, operating margins, taxes, capital expenditure and working capital.
Step 2: Determine the Discount Rate (WACC)
The next step is to determine the appropriate discount rate. For an enterprise DCF, the Weighted Average Cost of Capital (WACC) is commonly used. WACC reflects the required return of the company’s providers of debt and equity capital, weighted according to their respective proportions in the capital structure.
WACC = (E/V × Cost of Equity) + (D/V × Cost of Debt × (1 − Tax Rate))
The cost of equity is often estimated using the Capital Asset Pricing Model (CAPM), which incorporates the risk-free rate, the company’s beta and the expected market risk premium. The after-tax cost of debt reflects the tax deductibility of interest, where applicable.
Step 3: Estimate Terminal Value
A DCF normally forecasts cash flows only for a finite explicit period. Since a going concern is expected to operate beyond that period, a terminal value is required to capture the value of cash flows generated after the forecast horizon.
Two commonly used approaches are:
Perpetuity Growth Method: This method assumes that free cash flow grows at a stable, sustainable rate indefinitely.
TV = FCFₙ × (1 + g) / (WACC − g)
Here, g is the long-term growth rate. The growth assumption should generally be consistent with the long-term economic and industry environment.
Exit Multiple Method: Under this approach, the business is valued at the end of the forecast period using a market-based multiple, such as EV/EBITDA, applied to an appropriate financial metric.
Step 4: Discount the Cash Flows to Present Value
Once the forecast cash flows and terminal value have been estimated, each amount is discounted to its present value using the selected discount rate.
Discount Factor = 1 / (1 + WACC)^t
The present values of the forecast-period free cash flows and the discounted terminal value are then added together to determine the Enterprise Value.
Enterprise Value = PV of Forecast FCFs + PV of Terminal Value
Step 5: Determine Equity Value and Implied Share Price
Enterprise Value represents the value attributable to the operations of the business before considering certain financing claims. To arrive at Equity Value, debt and other relevant debt-like claims are generally deducted, while cash and cash equivalents are added, subject to the specific valuation framework.
Equity Value = Enterprise Value − Debt + Cash
The implied value per share is then calculated by dividing Equity Value by the relevant number of outstanding shares, with appropriate adjustments where applicable.
Implied Value per Share = Equity Value / Shares Outstanding
4. Sensitivity Analysis and Scenario Testing
DCF valuation is highly sensitive to assumptions, particularly the discount rate and terminal growth rate. A small change in either variable can materially change the estimated enterprise value. Analysts therefore commonly use sensitivity tables and scenario analysis to examine how valuation changes under different assumptions.
Scenario analysis may consider cases such as a base case, higher-growth case and lower-growth case. The purpose is not to produce a single unquestionable value, but to understand the range of values implied by different operating and financial assumptions.
5. Key Assumptions in a DCF Model
- Revenue growth and the expected development of the company’s market.
- Operating margins and the company’s ability to convert revenue into operating profit.
- Tax rates and the expected tax profile of the business.
- Capital expenditure required to maintain and expand operations.
- Working capital requirements and changes in operating assets and liabilities.
- Long-term sustainable growth after the explicit forecast period.
- Cost of capital and the risks associated with the company and its cash flows.
6. Advantages of DCF Valuation
- It focuses on the fundamental cash-generating ability of a business.
- It provides a framework for linking operating assumptions to valuation.
- It can be tailored to the specific characteristics and expected future performance of a company.
- It helps analysts evaluate how changes in growth, margins, investment and risk affect value.
7. Limitations of DCF Valuation
The principal limitation of DCF valuation is its dependence on assumptions. Forecasting future cash flows involves uncertainty, and estimates of WACC and terminal growth can materially affect the result. The terminal value can also represent a substantial portion of total enterprise value, making the model particularly sensitive to long-term assumptions.
DCF analysis may also be more difficult to apply to early-stage companies, businesses with highly volatile cash flows, or companies undergoing major structural changes. In such situations, analysts may supplement DCF with other approaches, including comparable-company and precedent-transaction analysis, rather than relying on a single valuation method.
Conclusion
Discounted Cash Flow valuation provides a structured way to estimate the intrinsic value of a business by translating expected future free cash flows into present value. Its five core stages—forecasting free cash flow, determining the discount rate, estimating terminal value, discounting the cash flows and deriving equity value—form the foundation of the methodology.
A DCF model should not be viewed as a precise prediction of what a company is worth. Rather, it is a disciplined analytical framework whose usefulness depends on the quality, consistency and reasonableness of its assumptions. Combining DCF with sensitivity analysis and other valuation techniques can provide a more comprehensive understanding of a company’s value.
Quick DCF Flow
Forecast FCF → Determine WACC → Calculate Terminal Value → Discount Cash Flows → Equity Value → Implied Share Price
Written by
Abhishek Kumar
Basics Of Valuation